Philadelphia multifamily construction deliveries slow to start 2026
Q1 2026
Philadelphia multifamily market overview
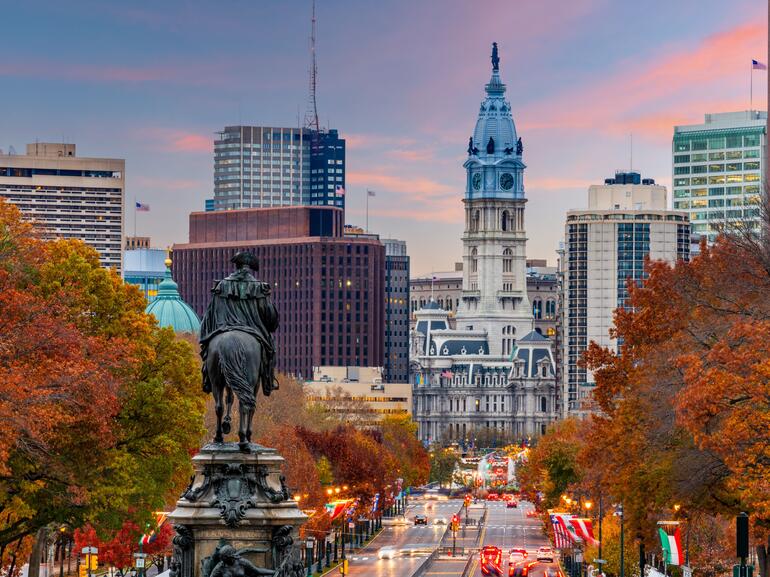
Greater Philadelphia entered 2026 past the peak of its recent supply cycle. First-quarter deliveries fell to their lowest level in several years, and full-year completions are expected to finish below 2025, giving owners some relief from the pressure of new supply that has occurred since 2023. The relief will not be felt evenly. The urban core still accounts for roughly 75% of units scheduled to deliver this year, while the modest suburban vacancy uptick in the first quarter reflected new projects opening in counties that consistently have seen little new construction. Job growth also slowed sharply, with employers adding roughly 5,000 positions year over year, though healthcare remained the main source of demand and continues to be the main employment driver for the region.
Philadelphia multifamily investment activity carried its 2025 momentum into the new year, with first-quarter deal count ahead of the same period last year, even as dollar volume eased. Private and regional buyers accounted for most activity, targeting mid-size assets while larger institutional capital remained selective. Average deal size was below $30 million, roughly half the level recorded in recent years, and no transaction exceeded $90 million. The smaller average transaction size reflects a transaction pool weighted toward older, lower-basis assets.
Looking ahead for Philadelphia
The Philadelphia market enters 2026 transitioning from heavy absorption toward steadier conditions. Completions are projected at roughly 7,000 units in 2026, in line with the long-term average and below the elevated 2024 and 2025 totals, with the bulk weighted toward the second half of the year. Urban projects make up close to three-quarters of expected completions, as developments that broke ground during the urban building boom come online. Units still under construction are split roughly evenly between urban and suburban, but later-cycle suburban starts mean nearly 70% of deliveries beyond 2027 are concentrated in the suburbs. Demand is expected to stay supportive even as job growth cools, with housing costs continuing to price out would-be buyers and the healthcare sector anchoring the employment base. Vacancy is projected to hold near current levels while rents continue their measured climb.
Transaction activity is expected to remain elevated through 2026, building on a first quarter in which deal counts ran well ahead of the prior-year pace. The repricing that constrained activity through 2023 and much of 2024 has largely played out, while the broader buyer pool that emerged in 2025 has carried momentum into the new year. Dollar volume has been slower to recover, limited by fewer large trades, but should strengthen as institutional capital re-engages with greater clarity around the urban supply outlook. Healthcare and life sciences employment growth, anchored by ongoing development in University City and at the Navy Yard, continues to support demand in the metro’s strongest submarkets. For stabilized, well-located assets with limited near-term supply exposure, steady fundamentals and a thinner delivery pipeline point to firmer pricing and activity as the year progresses.
Connect with our Philadelphia team today
For a more complete analysis of the supply, demand, vacancy, rent and investment trends in the Philadelphia market, download and read the full report below.
The Northmarq Philadelphia provides a broad range of commercial real estate solutions across debt, equity and investment sales. Engage with our Philadelphia team today.
Get the Q1 2026 Philadelphia report
Insights
Research to help you make knowledgeable investment decisions