Nashville multifamily market fundamentals strengthen at midyear
Q2 2026
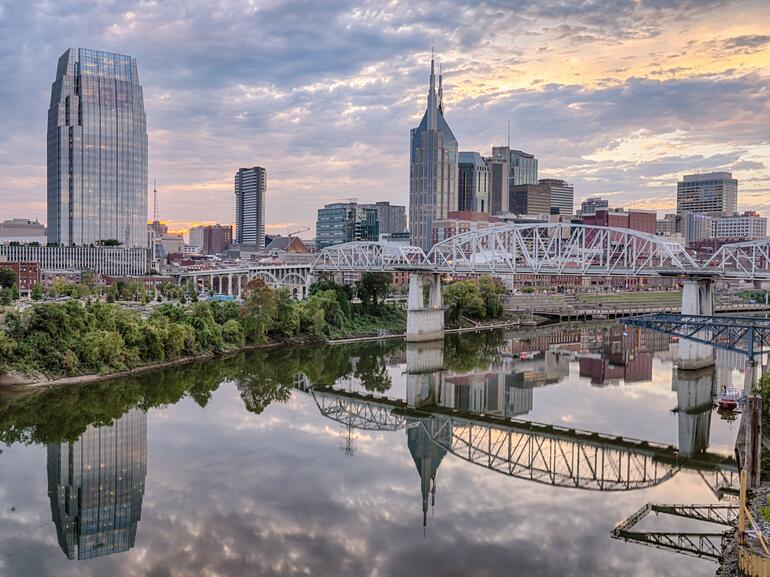
Nashville multifamily market overview
Nashville's recovery gained momentum in the second quarter as vacancy recorded its largest quarterly decline since the supply cycle began and rents posted their strongest quarterly increase since 2022. Vacancy fell 80 basis points from the prior quarter to 7.8% and was down 30 basis points year over year. The improvement coincided with trailing 12-month absorption of approximately 8,900 units, which exceeded deliveries by 11%. Supply conditions have also become more favorable as completions continue to decline from their 2023 peak and the development pipeline contracts. Performance gains were evident across the market, though middle-tier properties led the recovery. Class B assets recorded the largest occupancy improvement among asset classes, while Class C properties generated the strongest annual rent growth. Asking rents increased 1.7% during the second quarter to $1,723 per month, the largest quarterly gain in four years.
Nashville's investment market was defined more by composition than volume during the first half of the year. Transaction counts remained generally consistent with recent years, extending a period of stability following the slowdown from 2021 highs. Sales activity, however, was concentrated in lower-tier assets. Just two Class A properties traded during the first half, marking a notable departure from historical patterns in which institutional-quality assets regularly account for a significant share of activity. As a result, the year-to-date median sale price fell 6% from 2025 to $214,600 per unit. Despite a shift toward lower-tier product, cap rates averaged 5.1% in the second quarter, representing a 20-basis-point decline from one year earlier.
Looking ahead for Nashville
Permitting activity may prove to be one of the most significant indicators of Nashville's long-term outlook. With permits tracking well below the five-year average, the current pace suggests a much more constrained supply environment in 2028 and 2029 than the market has experienced during this cycle. In the near term, the development pipeline continues to contract, and completions are projected to decline again this year, reducing competitive pressure from new deliveries. At the same time, employment growth is expected to accelerate through year-end, supported by ongoing corporate investment and relocation activity. As supply growth moderates and demand remains supported by job creation, vacancy is expected to continue improving, creating conditions for rent growth.
Owners of recently delivered communities have generally remained focused on lease-up and income stabilization before pursuing a sale. As those properties mature, the market could see a broader mix of institutional-quality offerings, providing additional opportunities for investors. Increased activity among stabilized assets could support pricing trends, particularly as market fundamentals continue to improve. At the same time, cap rates have begun to compress, reflecting sustained investor interest and growing confidence in the market’s outlook.
Connect with our Nashville team today
For a more complete analysis of the supply, demand, vacancy, rent and investment trends in the Nashville multifamily market, download and read the full report below.
The Northmarq Nashville office provides a broad range of commercial real estate solutions across debt, equity and investment sales. Engage with our Nashville team today.
Get the Q2 2026 Nashville report
Insights
Research to help you make knowledgeable investment decisions