
Houston multifamily vacancies trend lower at midyear
Q2 2026
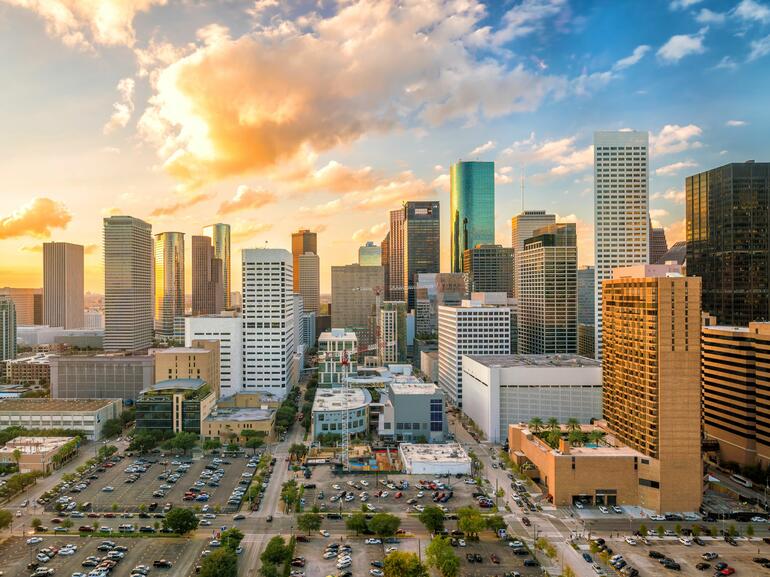
Houston multifamily market overview
After supply growth had been gradually tapering for much of the past 18 months, vacancy across the Houston multifamily market finally declined at a meaningful pace. The 40-basis-point decrease during the second quarter was the largest improvement in nearly five years. A surge in renter demand fueled the improvement; net absorption totaled more than 6,500 units during the quarter, up more than 60% from the same period last year. While absorption was elevated and the vacancy rate dipped, rents were mostly flat in the second quarter. Rents had posted steady gains at the beginning of the year, but that momentum was not sustained during the most recent quarter. Current rents are still slightly higher than they were one year ago.
The Houston multifamily investment market got off to a strong start this year, though sales activity slowed from the first quarter to the second quarter. Despite the recent pullback, year-to-date sales remain 31% above the level recorded during the same period in 2025. Investors have been particularly active in Northwest Houston, where transaction velocity has nearly matched the submarket's full-year 2025 total and accounts for 16% of all sales, tying Southeast Houston for the regional lead. Activity has been concentrated along the FM 1960 corridor from Route 290 to Westfield, with a cluster of transactions near Westfield. Most properties changing hands in the area were built between the 1970s and 1990s, though several assets completed within the past six years have also traded.
Looking ahead for Houston, TX:
Houston multifamily fundamentals are expected to strengthen through the end of the year. Deliveries are forecast to decline, as much of this year’s anticipated supply growth has already occurred. More modest completion levels are expected to extend into 2027 and potentially 2028, as multifamily permitting has remained light. Preliminary forecasts call for roughly 5,600 units to deliver in 2027, a figure that would represent the lowest annual completions total in nearly 15 years. Development activity is scheduled to decline significantly in Bear Creek/Copperfield, where the current pipeline contains no planned deliveries beyond early 2027. As supply-side pressures ease, vacancy should trend lower. Over the long term, market conditions may gradually return toward the historical vacancy average of approximately 6%.
Transaction activity in Houston's multifamily investment market is expected to accelerate in the second half, with full-year sales likely to exceed the lighter levels recorded during the past two years. Investment activity should remain balanced across the metro, and while assets from a variety of vintages are expected to continue changing hands, buyer interest may increasingly shift toward newer properties. Nearly a dozen 2020s-vintage assets have sold year to date, while Class A fundamentals strengthened as vacancy declined and rent growth outpaced the market average. Even so, value-add opportunities should remain prevalent, as rents at Class B and Class C properties have been largely stagnant despite improving occupancy conditions.
Connect with our Houston team today
For a more complete analysis of the supply, demand, vacancy, rent and investment trends in the Houston multifamily market, download and read the full report below.
The Northmarq Houston office provides a broad range of commercial real estate solutions across debt, equity and investment sales. Engage with our Houston team today.
Get the Q2 2026 Houston report
Insights
Research to help you make knowledgeable investment decisions