
Elevated absorption supports fundamentals for Denver’s multifamily market
Q2 2026
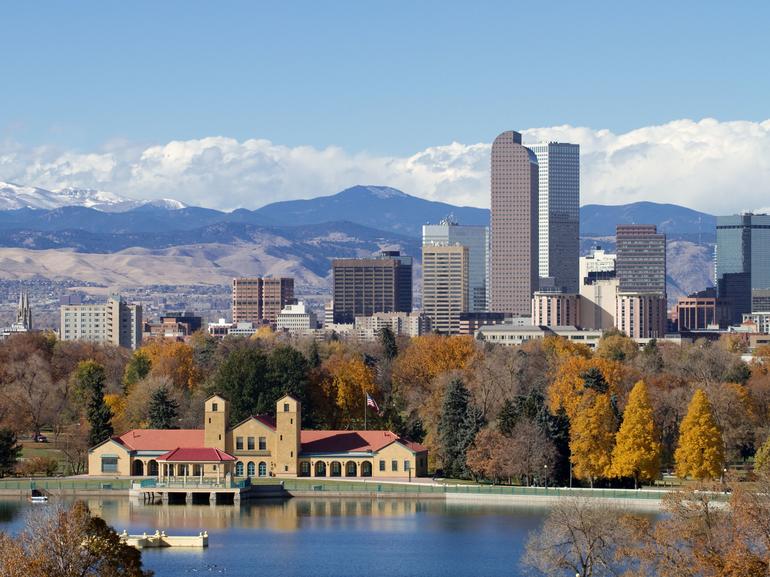
Denver multifamily market overview
Stabilized vacancy improved across the Denver region during the second quarter, although two vintages remain worse off than one year ago. Buildings built in the 1970s posted the highest overall vacancy and the largest year-over-year increase, while units built in the 2020s posted a slight annual increase. For the newest communities, the pressure reflects ongoing lease-up activity following the 2024 delivery peak, as many newer builds continue competing against other recently completed projects. The 1970s cohort stands out for different reasons. It holds the highest vacancy rate in the metro and the lowest average rents, and was the only vintage to post rent declines during the quarter. Operating strength now sits in the middle of the vintage curve, with 1990s product recording the metro's lowest vacancy rate at 4.2%.
Investment activity during the first half of 2026 was split between older value-add product and newer core-quality assets, though the pricing gap between the two narrowed considerably. Properties built before 1980 traded from $95,000 per unit to $176,000 per unit, with activity concentrated in Windsor, Goldsmith and central Denver. Newer product ranged from $170,000 per unit in the Golden Triangle to $630,000 per unit in Cherry Creek. Communities that last traded near the 2021 and 2022 pricing peak resold during the most recent period at roughly half their prior per-unit values, with markdowns occurring across both recent construction and 1970s-era assets. Capital remained concentrated in Denver proper, while the suburban growth corridors that drove volume in 2025 recorded comparatively limited activity.
Looking ahead for Denver:
The Denver multifamily market is expected to continue to be impacted by new supply in the coming periods. While delivery totals are not expected to approach peak levels from 2024, an additional 4,800 units are expected to come online over the remainder of this year, while nearly 13,000 units are slated for completion in 2027. Because those developments are already underway, the 2027 influx of new supply is largely set regardless of future permitting activity trends. Communities currently in lease-up present another challenge, with roughly 11,100 units still unleased across the metro. Absorption will need to remain near recent levels to work through that inventory before the next round of deliveries arrives.
Multifamily sales activity is expected to strengthen through the second half of 2026. Transaction counts and total volume both trailed year-ago levels during the first half, and the deal mix skewed heavily toward older, value-add product. That composition should shift in the coming quarters. A significant volume of recently delivered communities is completing lease-up and moving into stabilized inventory, expanding the pool of newer assets available to buyers. Class A activity, nearly absent from the first-half transaction mix, is positioned to recover as this product becomes marketable. Deal flow should also broaden geographically, as first-half activity concentrated in a narrow set of submarkets where older product is clustered.
Connect with our Denver team today
For a more complete analysis of the supply, demand, vacancy, rent and investment trends in the Denver multifamily market, download and read the full report below.
The Northmarq Denver office provides a broad range of commercial real estate solutions across debt, equity and investment sales. Engage with our Denver team today.
Get the Q2 2026 Denver report
Insights
Research to help you make knowledgeable investment decisions