
Chicago multifamily rents on the rise, fueling sales activity
Q2 2026
Chicago multifamily market overview
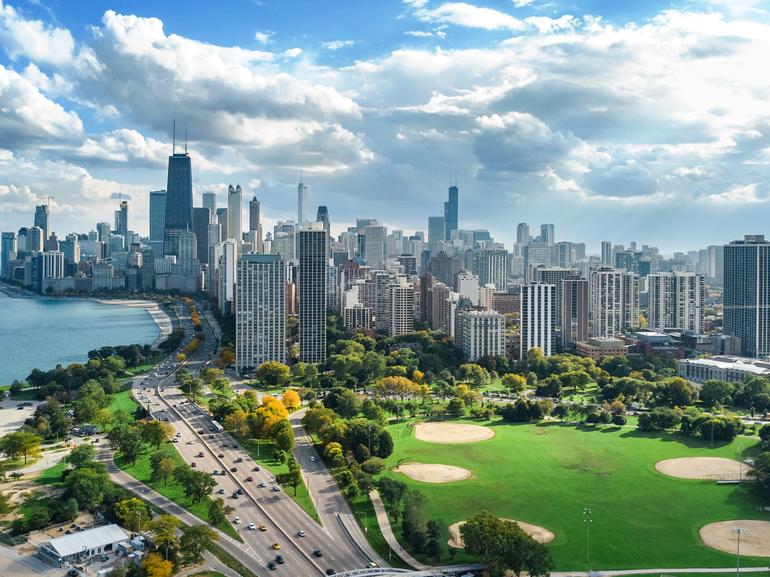
The Chicago multifamily market has been posting healthy operational performance in recent quarters. The area’s overall vacancy rate is up slightly compared to one year ago, and is about 70 basis points higher than the lows recorded in mid-2022. The overall average masks some of the strongest performances being recorded, particularly within the city limits. Three submarkets neighboring the lakefront, just north of downtown are recording the strongest vacancy performance. Lincoln Park has the lowest vacancy rate at 3.1% after dipping 30 basis points in the past year, while the nearby Lakeview and Rogers Park areas recorded the greatest year-over-year vacancy improvements. Rent growth was recorded across the market in both urban and suburban areas, though it was generally strongest towards the urban core. The Loop, along with the neighborhoods surrounding it, were the rent growth leaders in Chicago. Areas such as the West Loop, South Loop, River North, and Fulton Market all maintained similar rent growth in the past year, rising by an average of 5.5% to more than $3,000 per month.
The strong pace of multifamily investment activity was sustained during the second quarter, bringing the transaction count in the first half to its highest point in more than a decade. The greatest concentration of sales was in the downtown area, followed by transactions that were spread across the outlying suburbs near transit infrastructure such as Metra rail stations. Roughly half of all transactions were Class B properties, with the remainder split evenly between Class A and Class C. Cap rates averaged 6.0% during the first half, up 25 basis points compared to last year.
Looking ahead for Chicago:
Operating conditions in the Chicago multifamily market are projected to improve in 2026. While absorption and construction measures have been largely stable in relation to the market’s size, the recent rise in rents is the clearest signal of the improving health of area property fundamentals. Rent growth will remain persistent, fueled in part by the number of new units achieving higher rates while keeping occupancy tight. It is not just newer and top-tier properties that should keep a positive outlook. Class B and Class C absorption has improved this year after posting a few periods of net negative levels. Rents in Class B and Class C units have gained ground the fastest. Looking past 2026, the development pipeline has been shrinking and should continue to taper in coming months, which may help push vacancy below 5.0% in 2027.
The surge of multifamily sales in the first half of the year should ensure that 2026 is one of the most active years for investment sales in the past decade in Chicago, even if sales velocity slows during the second half. Investor demand is expected to persist in downtown neighborhoods, which already contain the greatest share of activity. Improving renter demand in Class B and Class C properties could spark investor interest outside of the top tier. This may be especially apparent in the outlying suburbs, particularly in areas such as Aurora and Naperville where vacancy rates have remained below the market average, and in areas such as Kane County, Lombard, and Glendale Heights where strong rent growth has persisted in recent periods.
Connect with our Chicago team today
For a more complete analysis of the supply, demand, vacancy, rent and investment trends in the Chicago multifamily market, download and read the full report below.
The Northmarq Chicago office provides a broad range of commercial real estate solutions across debt, equity and investment sales. Engage with our Chicago team today.
Get the Q2 2026 Chicago report
Read More
Insights
Research to help you make knowledgeable investment decisions