
Austin multifamily rents begin to reverse a three-year slide
Q2 2026
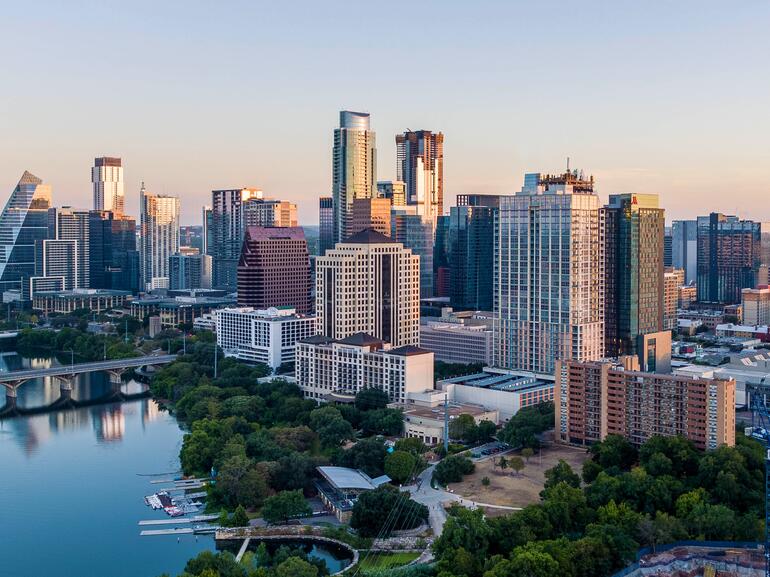
Austin multifamily market overview
The turn that Austin has been anticipating for several years may have begun to take shape during the second quarter, as slowing supply growth coincided with elevated demand. Deliveries declined sharply from the peaks recorded in 2024 and 2025, while quarterly absorption reached a new high. These forces combined to drive a sharp quarterly vacancy improvement and helped end a three-year stretch of rent declines. Class A properties, which have been particularly hard-hit in recent years, posted the largest vacancy improvement of any asset class. Underpinning these gains is a strengthening labor market, with employment growth once again outpacing national benchmarks.
Austin's investment market has gained momentum to this point in 2026. Transaction activity during the first half reached its highest level since 2022, supported by a handful of Class B property sales along the northern suburban corridor. While per-unit prices in transactions where prices are available showed some slight declines, cap rates have compressed during the past year. This shift to slightly lower cap rates may be an early signal that investor sentiment in Austin is beginning to improve as the pace of construction slows and rents stabilize.
Looking ahead for Austin
While the Austin multifamily market is still hampered by elevated delivery totals from prior years, the local construction pipeline is thinning, and supply-side pressures are likely to ease in the coming years. Deliveries are projected to decline 24% from the 2024-2025 peak, while multifamily permitting activity has fallen sharply from levels recorded earlier in the decade, signaling a continued slowdown in deliveries is likely in the coming years. For the remainder of 2026, continued job growth should drive absorption. This renter demand for units is expected to result in further vacancy improvement and a more stable rent environment.
For investors, Austin has moved beyond the period when the primary question was whether conditions had reached a bottom. Apartment fundamentals have begun to improve after soft conditions in recent years. Cap rates have stabilized in recent quarters, while transaction activity has increased, suggesting improving investor sentiment. The performance in Class A properties will be closely tracked by investors during the next phase of the cycle. If supply continues to moderate and demand remains healthy, investment activity could broaden in the coming years.
Connect with our Austin team today
For a more complete analysis of the supply, demand, vacancy, rent and investment trends in the Austin multifamily market, download and read the full report below.
The Northmarq Austin office provides a broad range of commercial real estate solutions across debt, equity and investment sales. Engage with our Austin team today.
Get the Q2 2026 Austin report
Insights
Research to help you make knowledgeable investment decisions